 PropAce
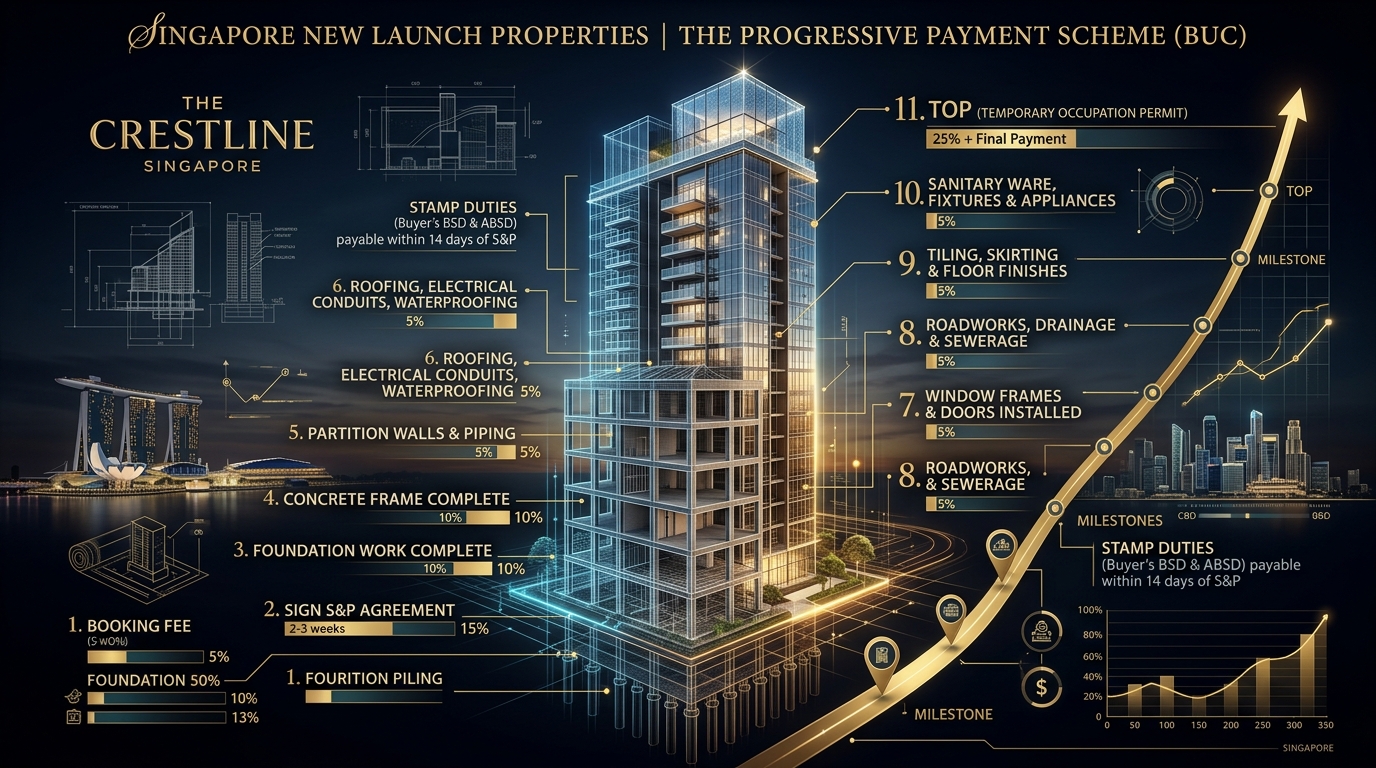
When purchasing an uncompleted private residential property in Singapore (commonly known as Building-Under-Construction or BUC), one of the most attractive financial mechanisms is the Progressive Payment Scheme.
Unlike completed resale properties where the entire purchase price is disbursed upon legal completion, the BUC schedule ties financial disbursements directly to physical construction milestones. This framework—codified under the Housing Developers (Control and Licensing) Act—protects buyers from developer insolvency and significantly lowers holding costs during the 3 to 4-year construction window.
1. The Statutory Downpayment Phase (First 20% to 25%)
Before bank loan drawdowns commence, the buyer must satisfy the initial downpayment milestones using cash and CPF Ordinary Account (OA) savings:
Stage 1: Booking Fee (5% Cash)
- When Due: Day 1 upon granting of the Option to Purchase (OTP).
- Payment Method: Strictly cash or cheque/cashier's order (CPF savings cannot be used for this initial 5%).
- Legal Effect: Secures the unit and initiates the developer's 14-day statutory window to deliver the formal Sale & Purchase (S&P) Agreement.
Stage 2: Exercise Option & Signing S&P (15% Cash / CPF OA)
- When Due: Within 3 weeks of receiving the official S&P Agreement from the developer's lawyers.
- Payment Method: Cash, CPF Ordinary Account savings, or a combination.
- Stamp Duties: Buyer's Stamp Duty (BSD) and any applicable ABSD must be paid to IRAS within 14 calendar days of exercising the S&P.
Balance Downpayment (5% to 15%)
If taking a standard 75% Loan-to-Value (LTV) bank mortgage, the remaining 5% downpayment is drawn down from CPF OA or cash upon the completion of the foundation phase.
2. The 11 Construction Milestone Stages
Under Singapore statutory rules, the developer cannot simply demand funds on an arbitrary calendar schedule. Each payment tranche is triggered strictly when an independent registered Architect issues a formal statutory Certificate of Completion for that specific stage.
| Milestone # | Construction Milestone | Statutory Stage % | Cumulative % | Typical Timeline | Funding Source |
|---|---|---|---|---|---|
| 1 | Booking Fee (OTP) | 5% | 5% | Month 0 | Cash Only |
| 2 | Signing S&P (Exercise OTP) | 15% | 20% | Month 2 | Cash / CPF OA |
| 3 | Completion of Foundation Work | 10% | 30% | ~Month 6 | Cash/CPF (5%) + Bank Loan (5%) |
| 4 | Reinforced Concrete (RC) Framework | 10% | 40% | ~Month 12 | Bank Loan |
| 5 | Partition Walls & Brickworks | 5% | 45% | ~Month 18 | Bank Loan |
| 6 | Roofing & Ceiling Installation | 5% | 50% | ~Month 22 | Bank Loan |
| 7 | Internal Plumbing, Electrical & Plaster | 5% | 55% | ~Month 26 | Bank Loan |
| 8 | Doors & Window Frames Installed | 5% | 60% | ~Month 30 | Bank Loan |
| 9 | Carpark, Roads, Drainage & Sewerage | 5% | 65% | ~Month 34 | Bank Loan |
| 10 | Temporary Occupation Permit (TOP) | 25% | 90% | ~Month 38 | Bank Loan |
| 11 | Certificate of Statutory Completion (CSC) | 15% | 100% | ~Month 48 | Bank Loan (Escrow with SAL) |
3. How Monthly Mortgage Payments Escalate: A Worked Example
The core strategic advantage of the Progressive Payment Scheme is that you only pay interest and principal on the cumulative amount of loan disbursed so far, NOT the full loan facility.
Consider a buyer purchasing a S$2,000,000 new launch condominium with a 75% bank loan (S$1,500,000) at an interest rate of 3.5% p.a. over a 25-year tenure:
`` Disbursed Loan Stage by Stage: • Foundation Complete (Stage 3): Only S$100,000 loan drawn --> Est. Monthly Payment: S$501 / month • Concrete Framework (Stage 4): S$300,000 loan drawn --> Est. Monthly Payment: S$1,502 / month • Partition Walls (Stage 5): S$400,000 loan drawn --> Est. Monthly Payment: S$2,002 / month • Roofing (Stage 6): S$500,000 loan drawn --> Est. Monthly Payment: S$2,503 / month • Plumbing & Plaster (Stage 7): S$600,000 loan drawn --> Est. Monthly Payment: S$3,004 / month • Doors & Windows (Stage 8): S$700,000 loan drawn --> Est. Monthly Payment: S$3,504 / month • Roads & Carpark (Stage 9): S$800,000 loan drawn --> Est. Monthly Payment: S$4,005 / month • TOP Keys Collection (Stage 10): S$1,300,000 loan drawn --> Est. Monthly Payment: S$6,508 / month • Legal Completion CSC (Stage 11): S$1,600,000 (100% drawn) --> Est. Monthly Payment: S$8,010 / month ``
The Upgrader's Advantage: For homeowners who currently own an HDB flat or existing property, this gradual escalation means you are not saddled with a full S$8,000 monthly mortgage while waiting for construction to finish. During the first two years of construction, your monthly commitment remains well under S$2,500/month, allowing you to comfortably service your existing home loan.
4. Key Statutory Rules to Keep in Mind
1. The 14-Working-Day Notice Window
Once the project architect certifies completion of a milestone, the developer will serve formal notice to your conveyancing lawyer. By statutory law, payment must reach the developer's project account within 14 calendar days. Your conveyancing lawyer will immediately instruct your financing bank to disburse the loan tranche.
2. Late Payment Interest Penalties
Under the Standard Form of Sale and Purchase Agreement, failing to disburse within the 14-day window triggers contractual late interest (statutorily pegged at Prime Lending Rate + 2%). Ensure your loan offer is unconditionally accepted and legal conveyancing instructions are lodged well before the foundation stage.
3. Escrow Protection at CSC
The final 15% milestone upon legal completion is not handed directly to the developer. By statutory rule, 13.5% is held in escrow by the Singapore Academy of Law (SAL) for 12 months (the Defects Liability Period). If the developer fails to rectify defects reported by owners, SAL can release escrow funds to rectify the issues.
5. Next Steps
To model your exact stage-by-stage progressive payment schedule, simulate downpayment splits, and calculate monthly cash commitments:
👉 Explore the interactive PropAce BUC Progressive Payment Calculator.